
Choosing the right bankruptcy path is one of the most critical financial decisions you will ever make. The difference between Chapter 7 and Chapter 13 is not just procedural; it fundamentally alters your ability to keep assets, discharge debts, and rebuild credit. According to recent judicial statistics, Chapter 7 filings consistently outnumber Chapter 13 cases by a significant margin, reflecting its role as the primary tool for immediate debt relief. Understanding these distinctions is essential for anyone facing overwhelming financial pressure in California. (Bankruptcy What s) (Contact Us)
Understanding Chapter 7 Liquidation
Chapter 7 bankruptcy is often referred to as "straight bankruptcy" or "liquidation." It is designed for individuals who cannot pay their debts and have limited income. The primary goal is to provide a fresh start by discharging most unsecured debts, such as credit card balances, medical bills, and personal loans. (Frequently Asked Questions)
When you file for Chapter 7, a court-appointed trustee reviews your case to identify any non-exempt assets. These assets may be sold to pay off creditors. However, California exemption laws are robust and protect many essential items, including your primary residence, vehicle, and personal belongings, provided you stay within specific equity limits. For most filers, Chapter 7 results in the complete elimination of qualifying debts without the need to repay a portion of them. (About)
This process is typically faster than other forms of bankruptcy. The discharge usually occurs within three to six months after filing. This rapid resolution allows individuals to move forward with their financial lives much sooner than those pursuing other options. If you are struggling with unsecured debt and meet the income requirements, Chapter 7 is often the most efficient path to relief.
Understanding Chapter 13 Reorganization
Chapter 13 bankruptcy is known as a "wage earner's plan" or "reorganization." It allows individuals with a regular income to develop a plan to repay all or part of their debts over time. Instead of liquidating assets, you keep your property and make monthly payments to a trustee, who then distributes the funds to your creditors.
The repayment plan typically lasts three to five years, depending on your income relative to the median income in your state. During this period, you must adhere to a strict budget and make consistent payments. Chapter 13 is particularly useful for those who want to stop foreclosure on their home, catch up on missed mortgage payments, or protect assets that exceed the exemption limits available in Chapter 7.
Another significant advantage of Chapter 13 is its ability to handle secured debts differently. It can strip off second mortgages if the home's value is less than the first mortgage balance. It also allows you to pay priority debts, such as taxes and child support, over the life of the plan rather than all at once. This structure provides breathing room for those who need more time to get back on their feet.
Eligibility and Means Test Analysis
Eligibility for Chapter 7 versus Chapter 13 depends heavily on your financial situation. The most critical factor for Chapter 7 is the "means test." This test compares your median income to the median income in your state for a household of your size. If your income is below the median, you generally qualify for Chapter 7. If it is above, the test calculates your disposable income to determine if you can repay a portion of your debts.
Chapter 13 has different eligibility criteria. You must have a regular source of income to fund the repayment plan. Additionally, there are debt limits. As of the latest updates, unsecured debts must be less than a specific threshold, and secured debts must also fall below a certain limit. These limits are adjusted periodically for inflation. If your debts exceed these caps, you may be forced into Chapter 13 or another form of relief.
Understanding these thresholds is vital. A bankruptcy attorney can perform a detailed means test analysis to determine which chapter is legally available to you. This analysis considers your income, expenses, and family size to provide an accurate assessment of your options.
Asset Protection and Home Equity
One of the most common concerns for filers is what happens to their assets. In Chapter 7, non-exempt assets are liquidated. However, California's exemption laws are designed to protect what matters most to you. For example, you can exempt a certain amount of equity in your primary home. If your equity is within this limit, you keep your house. If it exceeds the limit, you might lose it unless you can pay the difference to the trustee.
Chapter 13 offers a different approach to asset protection. Because you are repaying debts over time, you can often keep assets that would be lost in Chapter 7. This is particularly true for homes with high equity. By catching up on missed payments through the repayment plan, you can prevent foreclosure and retain ownership. This makes Chapter 13 an attractive option for homeowners who are behind on payments but have the income to sustain a repayment plan.
Vehicle equity is another key consideration. California allows you to exempt a certain amount of equity in one vehicle. If your car's value is within this limit, it is protected in Chapter 7. In Chapter 13, you can often reduce the balance on a second car to the value of the vehicle, potentially lowering your monthly payments.
Cost and Duration of Proceedings
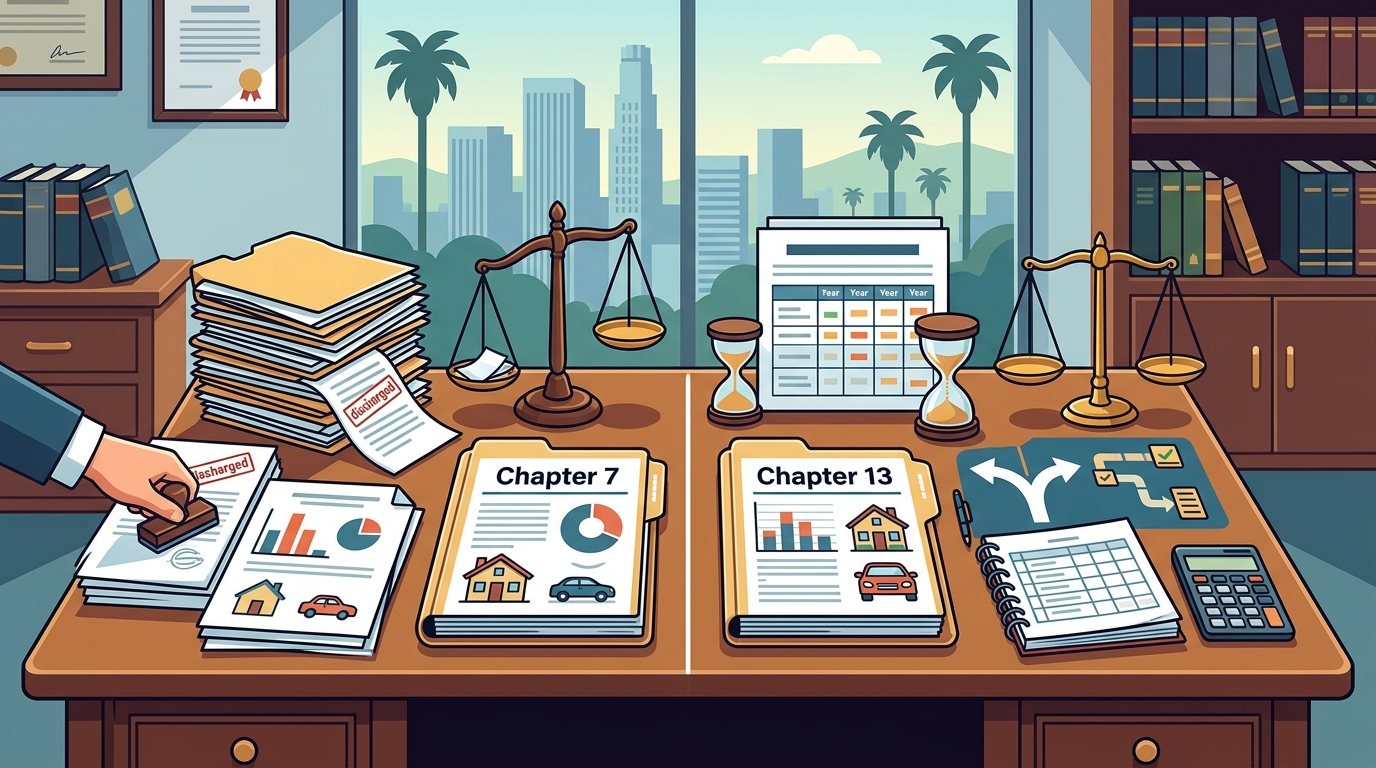
The cost and duration of bankruptcy proceedings vary significantly between Chapter 7 and Chapter 13. Chapter 7 is generally less expensive and faster. Filing fees are lower, and attorney fees are typically structured to be paid upfront or in a short-term plan. The entire process usually concludes within six months.
Chapter 13 is more complex and costly. Filing fees are higher, and attorney fees are often paid over the life of the repayment plan. The total cost is higher because you are repaying a portion of your debts. The duration of the case is also longer, lasting three to five years. During this time, you are under the supervision of the bankruptcy court and the trustee.
Despite the higher cost, Chapter 13 can be more cost-effective in the long run for some individuals. If you need to save your home or car, the cost of losing the asset may far exceed the cost of the bankruptcy. PM Bankruptcy helps clients evaluate these long-term financial implications to make an informed decision.
Detailed Comparison Summary
The following table summarizes the key differences between Chapter 7 and Chapter 13 bankruptcy. This comparison is designed to help you understand the structural differences at a glance.
| Feature | Chapter 7 | Chapter 13 |
|---|---|---|
| Primary Goal | Debt Discharge | Debt Reorganization |
| Duration | 3-6 Months | 3-5 Years |
| Asset Liquidation | Non-exempt assets sold | Assets retained |
| Repayment Plan | None | Required (3-5 years) |
| Home Foreclosure | Cannot stop if behind | Can stop and cure arrears |
| Income Requirement | Pass means test | Regular income required |
| Debt Limits | No debt limits | Strict debt caps apply |
Key Takeaways
- Chapter 7 provides a faster discharge of unsecured debts, typically within six months.
- Chapter 13 allows you to keep assets and catch up on missed mortgage payments over three to five years.
- The means test is the primary determinant for Chapter 7 eligibility based on your income relative to the state median.
- California exemption laws protect significant equity in homes and vehicles for Chapter 7 filers.
- Chapter 13 is ideal for those who need to stop foreclosure or have debts exceeding Chapter 7 limits.
- PM Bankruptcy offers specialized guidance to navigate the complexities of both chapters effectively.
- Choosing the wrong chapter can lead to dismissal of your case or loss of valuable assets.
Frequently Asked Questions
Can I keep my house in Chapter 7 bankruptcy?
Yes, you can keep your house in Chapter 7 if your equity falls within California's exemption limits. If your equity exceeds these limits, you may need to consider Chapter 13 or other options.
What is the main difference between Chapter 7 and Chapter 13?
Chapter 7 discharges most unsecured debts without repayment, while Chapter 13 requires a three-to-five-year repayment plan to reorganize debts and protect assets.
How long does Chapter 13 bankruptcy last?
Chapter 13 bankruptcy typically lasts three to five years, depending on your income and the amount of debt you are repaying.
Do I have to pay all my debts in Chapter 13?
No, you do not have to pay all your debts in Chapter 13. The plan pays a portion of your unsecured debts based on your disposable income and other factors.
Can I file for bankruptcy if I have a high income?
If your income is high, you may not qualify for Chapter 7 due to the means test. However, you may still be eligible for Chapter 13 if you have a regular income and meet the debt limits.
What happens to my credit score after bankruptcy?
Bankruptcy will initially lower your credit score, but it allows you to start rebuilding credit immediately. Chapter 7 stays on your report for ten years, while Chapter 13 stays for seven years.
How much does it cost to file for bankruptcy?
Filing fees and attorney fees vary. Chapter 7 is generally less expensive overall due to its shorter duration, while Chapter 13 involves higher fees spread over the repayment period.
Contact PM Bankruptcy
Navigating the choice between Chapter 7 and Chapter 13 requires expert legal guidance. PM Bankruptcy is dedicated to helping individuals in California find the best path to financial freedom. Our team understands the nuances of federal and state laws and can provide personalized advice tailored to your unique situation. Do not let debt control your life. Contact PM Bankruptcy today to schedule a consultation and take the first step toward a fresh start.