
Who Can Stop a Home Foreclosure Before It Happens in Sacramento?
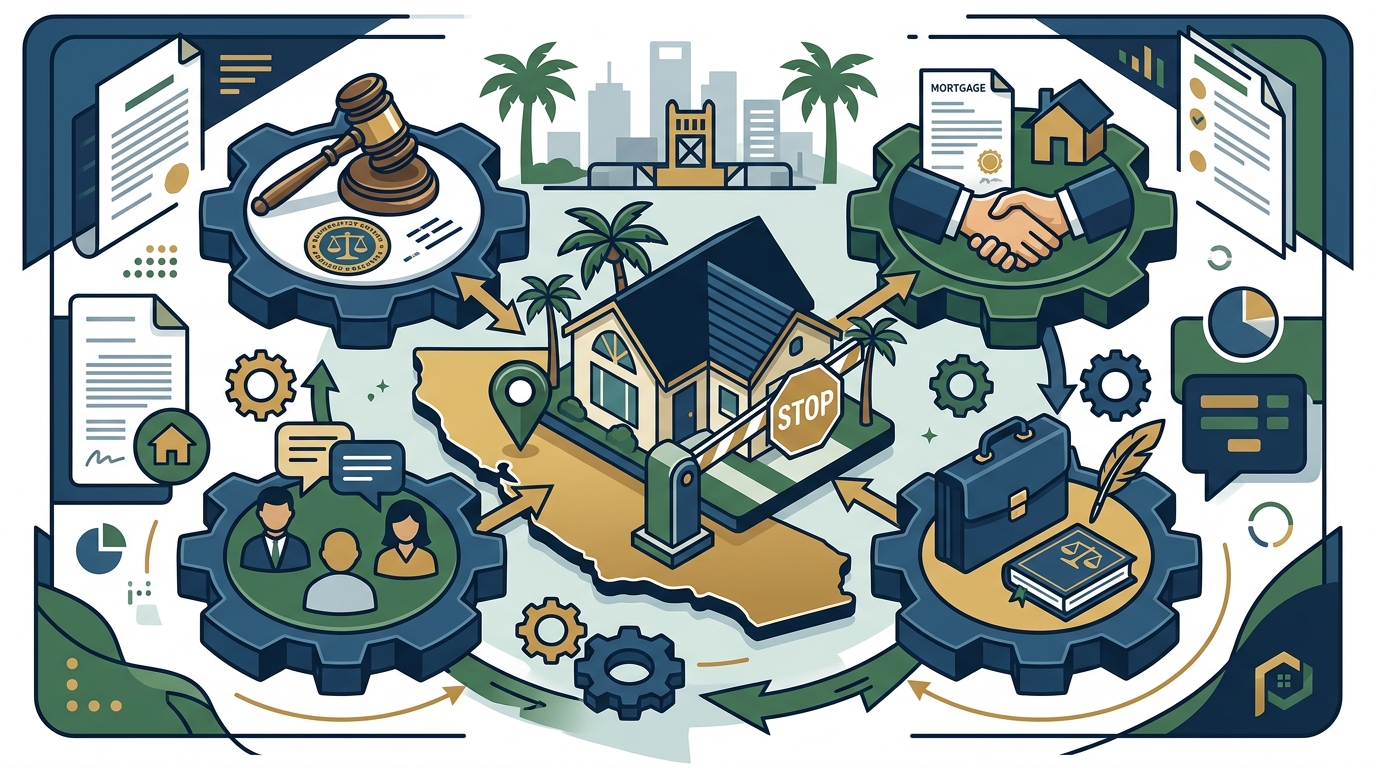
Several entities can stop a home foreclosure before it happens in Sacramento, including bankruptcy courts, mortgage servicers, HUD-approved housing counselors, and foreclosure defense attorneys. The most immediate legal mechanism is the automatic stay triggered by a bankruptcy filing. This guide covers the specific roles of these parties, the legal tools they use, and how homeowners in California can navigate the process with the help of pmbankruptcy. For additional details, review the .
Bankruptcy Automatic Stay
The most powerful legal tool to stop a foreclosure is the automatic stay. The automatic stay is a federal injunction that immediately halts all collection activities, including foreclosure proceedings, the moment a bankruptcy petition is filed. This protection applies to both Chapter 7 and Chapter 13 bankruptcy cases. For homeowners in Sacramento, filing for bankruptcy can freeze a foreclosure auction that is scheduled for days or weeks away. The stay remains in effect until the bankruptcy case is closed, dismissed, or the court grants the lender relief from the stay. This legal mechanism provides a critical window of time for the homeowner to reorganize their finances or negotiate a resolution with the lender. For additional details, review the Customer Experience.
Chapter 7 vs. Chapter 13 Stays
In a Chapter 7 case, the stay protects the home from foreclosure while the debtor's non-exempt assets are liquidated. If the homeowner has equity in the home, a Chapter 13 plan may be a better option to cure the mortgage default over time. The stay in a Chapter 13 case lasts for the duration of the repayment plan, which typically spans three to five years. This extended protection allows the debtor to catch up on missed payments while maintaining possession of the property. For additional details, review the Frequently Asked Questions.
Loan Modifications
A loan modification is a permanent change to the terms of a mortgage loan that makes the monthly payment more affordable. Lenders may agree to modify a loan by reducing the interest rate, extending the loan term, or capitalizing past-due payments. This option is often pursued through the lender's loss mitigation department. Homeowners must demonstrate a financial hardship and a reasonable ability to make the modified payments. A successful modification can prevent foreclosure by bringing the loan current and establishing a sustainable payment schedule. For additional details, review the About.
Eligibility for Modification
Eligibility for a loan modification depends on the type of loan and the lender's specific guidelines. Government-backed loans, such as those insured by the FHA or guaranteed by the VA, often have specific modification programs. Conventional loans may also be eligible for modifications under certain conditions. The homeowner must provide detailed financial documentation, including tax returns, pay stubs, and a hardship letter. The process can take several months, so it is important to start early.
Foreclosure Defense Attorneys
Foreclosure defense attorneys are legal professionals who specialize in representing homeowners in foreclosure proceedings. These attorneys review the lender's documentation to identify any procedural errors or violations of state and federal law. In California, strict compliance with foreclosure procedures is required, and any deviation can provide a defense for the homeowner. An attorney can file motions to dismiss the foreclosure action or negotiate a settlement with the lender. Their expertise is crucial in complex cases where the homeowner has significant equity or where the lender has made errors in the process.
Role in Negotiation
Attorneys often act as intermediaries between the homeowner and the lender. They can negotiate short sales, deeds in lieu of foreclosure, or loan modifications on behalf of the client. By handling the communication, the attorney ensures that the homeowner's interests are protected and that any agreements are legally sound. This professional representation can significantly improve the outcome of a foreclosure negotiation.
HUD Housing Counselors
HUD housing counselors are professionals who provide free or low-cost advice to homeowners facing foreclosure. The U.S. Department of Housing and Urban Development (HUD) approves these counseling agencies to ensure they meet specific standards. Counselors help homeowners understand their options, including loan modifications, forbearance, and bankruptcy. They can also assist in preparing the financial documents required for loss mitigation programs. While they cannot provide legal advice, their guidance is invaluable in navigating the complex landscape of foreclosure prevention.
How to Find a Counselor
Forbearance Agreements
A forbearance agreement is a temporary arrangement between a lender and a borrower that allows the borrower to make reduced or no payments for a specified period. This option is suitable for homeowners who are experiencing a temporary financial hardship, such as a job loss or medical emergency. At the end of the forbearance period, the borrower must resume regular payments and may need to pay the deferred amount in a lump sum or through a repayment plan. Forbearance can prevent foreclosure by providing immediate relief from payment obligations.
Types of Forbearance
There are different types of forbearance agreements, including short-term and long-term arrangements. Short-term forbearance may last a few months, while long-term forbearance can extend for a year or more. The specific terms depend on the lender's policies and the borrower's financial situation. It is important to understand the implications of deferred payments and how they will be handled at the end of the agreement.
Foreclosure Attorney Intervention
Strategic Timing
The timing of attorney intervention is critical. In California, the foreclosure process involves several stages, including the notice of default, notice of sale, and the actual auction. An attorney can intervene at any of these stages to halt the process. Early intervention is often more effective, as it allows for more time to negotiate and prepare a legal strategy. Waiting until the last minute can limit the available options and increase the risk of losing the home.
Mortgage Reinstatement
Mortgage reinstatement is the process of bringing a mortgage loan current by paying the past-due amount, including principal, interest, and fees. This option is available to homeowners who have the financial means to cure the default. Reinstatement can be done before or after the foreclosure sale, depending on state law. In California, homeowners have the right to reinstate their mortgage up to five business days before the foreclosure auction. This option allows the homeowner to keep their home and avoid the negative credit impact of a foreclosure.
Costs of Reinstatement
Loss Mitigation Options
Short Sales and Deeds in Lieu
A short sale is a transaction where the homeowner sells the property for less than the outstanding mortgage balance, with the lender's approval. A deed in lieu of foreclosure is a voluntary transfer of the property title to the lender in exchange for the cancellation of the mortgage debt. Both options can prevent a formal foreclosure from appearing on the credit report, although they still have a negative impact. These options are suitable for homeowners who cannot afford to keep the property but want to avoid the stigma of a foreclosure.
Housing Counseling
Housing counseling is a service provided by approved agencies that helps homeowners understand their financial situation and available options. Counselors review the homeowner's budget, income, and expenses to identify areas for improvement. They can also provide education on credit repair and financial planning. This service is often a prerequisite for certain loss mitigation programs. By engaging with a housing counselor, the homeowner gains a clear understanding of their financial health and the steps needed to stabilize their situation.
Benefits of Counseling
Foreclosure Attorney Representation
Choosing an Attorney
Key Takeaways
- The automatic stay in bankruptcy is the most immediate legal tool to stop a foreclosure.
- Loan modifications can make mortgage payments affordable by changing the loan terms.
- Foreclosure defense attorneys can identify legal errors and negotiate settlements.
- HUD housing counselors provide free or low-cost advice on foreclosure prevention options.
- Mortgage reinstatement allows homeowners to cure their default and keep their home.
- Early intervention and professional guidance are crucial for successful foreclosure prevention.
Frequently Asked Questions
Can a bankruptcy filing stop a foreclosure auction?
Yes, filing for bankruptcy triggers an automatic stay that halts all foreclosure proceedings, including scheduled auctions. This stay remains in effect until the bankruptcy case is resolved or the court grants relief to the lender.
What is the difference between a loan modification and a forbearance agreement?
A loan modification permanently changes the terms of the mortgage, such as the interest rate or loan term. A forbearance agreement is a temporary arrangement that allows the borrower to make reduced or no payments for a specified period.
Are HUD housing counselors free?
How long does the foreclosure process take in California?
The non-judicial foreclosure process in California typically takes at least three months from the recording of the notice of default to the foreclosure auction. The exact timeline can vary depending on the lender and any legal challenges.
Can I keep my home if I file for Chapter 7 bankruptcy?
It is possible to keep your home in a Chapter 7 bankruptcy if you are current on your mortgage or if you can bring the loan current through a reaffirmation agreement. If you are behind on payments, a Chapter 13 bankruptcy may be a better option to catch up on arrears.
What documents do I need for a loan modification?
You will typically need to provide tax returns, pay stubs, bank statements, and a hardship letter. The lender may also request a list of your monthly expenses and assets. It is important to provide accurate and complete documentation to support your application.
Is it worth hiring a foreclosure attorney?
Hiring a foreclosure attorney can be worth it if you have significant equity in your home, if the lender has made errors in the process, or if you are considering bankruptcy. An attorney can protect your rights and negotiate a favorable outcome.
What is a deed in lieu of foreclosure?
A deed in lieu of foreclosure is a voluntary transfer of the property title to the lender in exchange for the cancellation of the mortgage debt. This option can prevent a formal foreclosure from appearing on your credit report.
Conclusion
Stopping a home foreclosure in Sacramento requires a strategic approach and the right professional support. Whether through the legal protection of a bankruptcy automatic stay, the financial restructuring of a loan modification, or the guidance of a HUD housing counselor, there are multiple paths to preserving your home. The key is to act quickly and seek expert advice. pmbankruptcy provides comprehensive legal services for individuals and businesses facing financial distress in California. To discuss your options and protect your assets, contact pmbankruptcy today.