
Chapter 7 Bankruptcy Discharge Timing in California: Cost-Benefit Analysis
Understanding the precise timeline for a Chapter 7 bankruptcy discharge is critical for anyone navigating financial distress in California. The federal bankruptcy code mandates a specific window for this legal milestone, typically occurring approximately 60 to 90 days after the first meeting of creditors. This period is not merely administrative; it represents the exact moment when unsecured debts are legally extinguished, allowing debtors to reclaim their financial footing. According to the United States Courts, the average time from filing to discharge in Chapter 7 cases is roughly four months, though this can vary based on case complexity and court schedules. For residents of the Pacific Maritime region, knowing this timeline helps in planning credit recovery and asset protection strategies effectively. (Bankruptcy Statistics Updated) (pmbankruptcy com)
Understanding the Discharge Timeline
The journey to a Chapter 7 discharge begins the moment the petition is filed with the bankruptcy court. However, the discharge itself is not immediate. The law requires a waiting period to allow creditors to object to the discharge or to challenge the debtor's eligibility. This period is strictly defined by the Federal Rules of Bankruptcy Procedure. The first meeting of creditors, also known as the 341 meeting, is a pivotal event where the trustee questions the debtor under oath. After this meeting, the clock starts ticking for the discharge order. (Bankruptcy Statistics Data) (Customer Experience)
In California, particularly in districts like the Northern District which serves the Pacific Maritime area, court backlogs can influence the exact date of the discharge order. While the statutory minimum is 60 days after the 341 meeting, the actual issuance of the discharge order often takes longer due to administrative processing. It is essential to distinguish between the 341 meeting date and the discharge date. The former is a procedural step, while the latter is the legal conclusion of the debt relief process. The discharge order is the document that legally wipes out eligible debts. (Frequently Asked Questions)
During this waiting period, debtors must remain compliant with all court requirements. Failure to attend the 341 meeting or to provide requested documents can result in the dismissal of the case, effectively nullifying any progress made. This compliance is non-negotiable and forms the baseline for the cost-benefit analysis of proceeding with Chapter 7. (Bankruptcy California Courts) (About)
Cost of Delaying the Process
Time is a significant financial factor in bankruptcy cases. Delaying the discharge process incurs direct and indirect costs that can erode the benefits of filing. Direct costs include ongoing legal fees if the case requires additional hearings or motions to resolve complications. Indirect costs are often more substantial, including the continued accrual of interest on non-dischargeable debts and the psychological toll of prolonged financial uncertainty.
For many debtors, the delay also impacts their ability to rebuild credit. While a bankruptcy filing causes an immediate drop in credit scores, the discharge allows for the start of credit rebuilding programs. According to the Consumer Financial Protection Bureau, individuals who file for bankruptcy can often see significant credit score improvements within two to three years after discharge. However, every month of delay postpones this recovery window. This delay can be particularly costly for those seeking to purchase a home or secure a business loan in the competitive California market.
Additionally, the cost of maintaining legal representation during unnecessary delays can add up. While initial filing fees are fixed, additional legal work to resolve disputes or address trustee inquiries can increase the overall cost of the bankruptcy case. Therefore, minimizing delays is not just about speed; it is about cost efficiency. Efficient case management reduces the total financial burden of the bankruptcy process.
Benefits of Early Discharge
Securing a discharge as quickly as possible offers several strategic advantages. The primary benefit is the immediate relief from the burden of unsecured debt. This relief allows debtors to focus on budgeting and saving without the pressure of collection calls or legal threats from creditors. For individuals in California, this freedom can be crucial for maintaining stability in high-cost living areas.
Early discharge also accelerates the process of asset liquidation, if applicable. In Chapter 7 cases, non-exempt assets are sold by the trustee to pay creditors. A faster discharge means a quicker resolution of the estate, allowing the debtor to move forward with a clean slate. This speed is particularly beneficial for small business owners or individuals with complex financial situations who need to restructure their affairs promptly. (Discharge in Bankruptcy)
Furthermore, an early discharge can improve the debtor's standing in future financial transactions. Lenders and landlords often review bankruptcy history when evaluating applications. A recent discharge indicates that the debtor has completed the legal process and is no longer under the active supervision of the bankruptcy court. This status can make it easier to secure new credit or rental agreements. The discharge date serves as a clear marker of financial reset.
California Exemptions and Asset Protection
One of the most critical aspects of Chapter 7 bankruptcy in California is the selection of exemption systems. California offers two distinct sets of exemptions: System 1 and System 2. Debtors must choose one system for their entire case, and this choice significantly impacts what assets they can protect. System 1 generally offers higher homestead exemptions, which is beneficial for homeowners. System 2 offers broader exemptions for personal property and tools of the trade. (Statistics and Data)
The timing of the discharge does not change the exemption analysis, but it does affect when the debtor can fully utilize these protections. Once the discharge is granted, the debtor is free to use their exempt assets without fear of liquidation. This certainty is vital for planning future financial goals. For example, a debtor who protects their home under the homestead exemption can remain in their residence with greater confidence after discharge.
Understanding the nuances of California exemptions requires careful analysis of individual circumstances. Factors such as marital status, property value, and type of assets all play a role in determining the optimal exemption strategy. Proper exemption planning is essential to maximize asset protection in Chapter 7 cases. Consulting with experienced legal counsel is recommended to navigate these complexities effectively. (Data Analysis Bankruptcy)
Common Causes for Delay
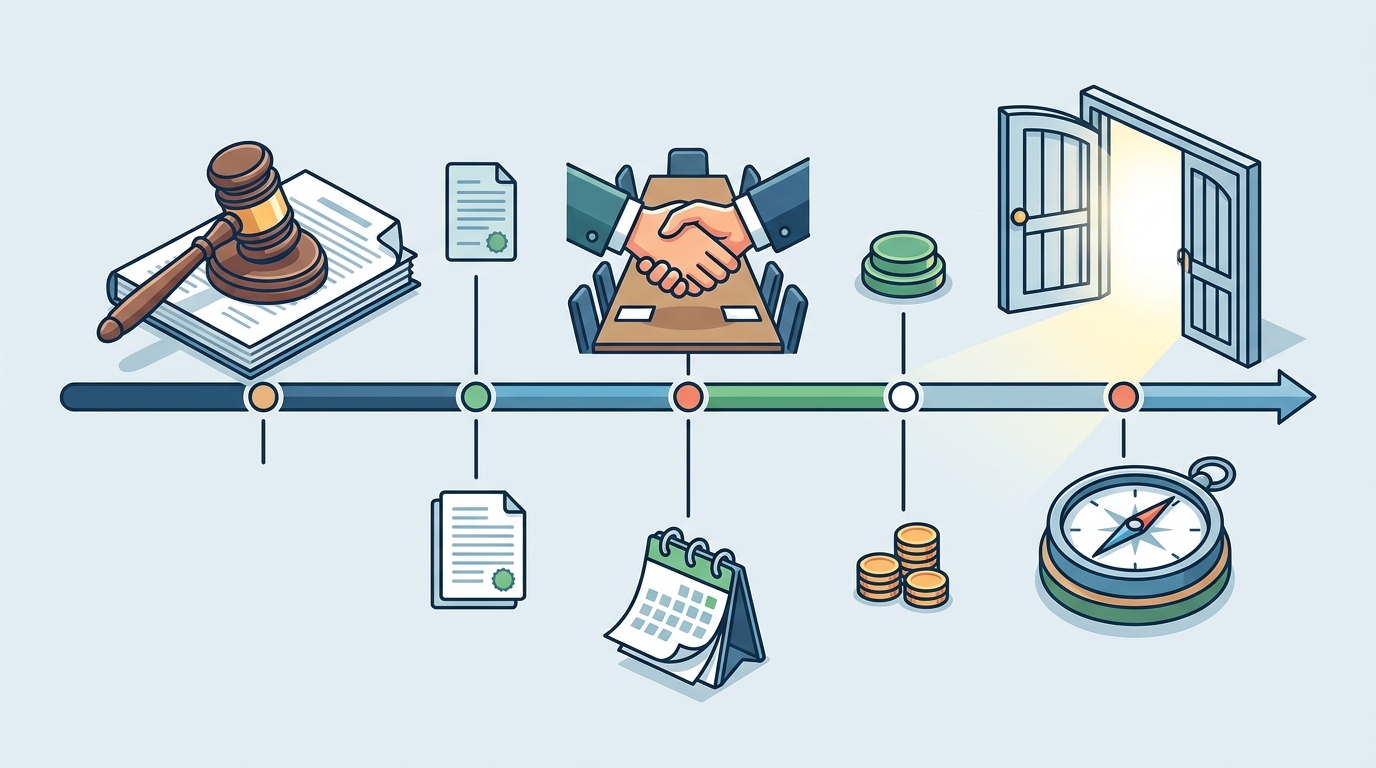
Several factors can contribute to delays in the discharge process. One common cause is the failure to attend the 341 meeting. If a debtor misses this meeting, the case may be dismissed, requiring a new filing and starting the timeline over. Another frequent cause is the trustee's request for additional documentation. Trustees must verify the accuracy of the debtor's schedules and ensure that all assets are properly disclosed.
Creditors may also file objections to the discharge, which can prolong the case significantly. These objections often arise from suspicions of fraud or concealment of assets. Resolving such objections requires legal proceedings that can extend the timeline by months or even years. Additionally, court backlogs in certain jurisdictions can slow down the issuance of discharge orders, even when all other requirements are met.
To minimize delays, debtors should ensure that all paperwork is accurate and complete before filing. Attending the 341 meeting on time and responding promptly to trustee inquiries are also crucial steps. Proactive communication with legal counsel can help identify and resolve potential issues before they cause delays.
Key Takeaways
- The Chapter 7 discharge typically occurs 60 to 90 days after the first meeting of creditors.
- Delays in discharge can increase legal costs and postpone credit recovery.
- Early discharge provides immediate relief from unsecured debt and collection activities.
- California debtors must choose between two exemption systems to protect their assets.
- Failure to attend the 341 meeting can result in case dismissal and timeline reset.
- Creditor objections and trustee inquiries are common causes of discharge delays.
- Efficient case management is essential for minimizing the financial impact of bankruptcy.
Frequently Asked Questions
How long does it take to get a Chapter 7 discharge in California?
In California, the average time to receive a Chapter 7 discharge is approximately four months from the filing date. This timeline includes the 341 meeting and the statutory waiting period for creditor objections.
Can I file for Chapter 7 bankruptcy if I own a home in California?
Yes, you can file for Chapter 7 bankruptcy even if you own a home. California's homestead exemptions may protect some or all of your equity, depending on the value of your property and the exemption system you choose. (Bankruptcy Statistics)
What happens if I miss my 341 meeting?
If you miss your 341 meeting, the bankruptcy trustee may dismiss your case. This dismissal would require you to file a new petition and start the process over, incurring additional costs and delays.
Are all debts eliminated in a Chapter 7 discharge?
No, not all debts are eliminated. Certain debts, such as student loans, child support, and alimony, are generally non-dischargeable. Additionally, debts incurred through fraud may also be excluded from the discharge.
How does Chapter 7 bankruptcy affect my credit score?
Chapter 7 bankruptcy will initially lower your credit score. However, many individuals see their scores improve within two to three years after discharge as they rebuild credit responsibly.
What is the difference between System 1 and System 2 exemptions in California?
System 1 offers higher homestead exemptions but lower personal property exemptions. System 2 offers broader exemptions for personal property and tools of the trade but lower homestead protection. The choice depends on your individual asset profile.
Can I keep my car in a Chapter 7 bankruptcy?
You may be able to keep your car if it is covered by California's vehicle exemption. If the equity in your car exceeds the exemption limit, the trustee may sell it to pay creditors.
Take Control of Your Financial Future
Navigating the complexities of Chapter 7 bankruptcy requires expert guidance and strategic planning. At Pacific Maritime Bankruptcy, we specialize in helping individuals and businesses in California achieve financial relief through efficient and effective bankruptcy solutions. Our team understands the local legal landscape and is committed to protecting your assets while guiding you toward a fresh start. Contact us today to schedule a consultation and learn how we can assist you in your journey to financial freedom.